Delivering energy infrastructure needs people, capability, and cohesion
Australia's energy transition requires more than technical plans. Discover four ways to build the people, culture and capability to deliver infrastructure at scale.


Change your location to view content tailored for you.
Over the past two years, Australia’s energy transition has quietly tipped into a new phase. When we look at where the money is going, a clear pattern emerges: investment is flowing into battery storage far faster than into new wind and solar.
That’s not a quirk of the market. It’s a signal.
Quarter after quarter, large-scale batteries are reaching financial close at a pace that would have been unthinkable even three years ago. Recent investment data shows:
On current trends, the storage build-out is at least aligned with Australian Energy Market Operator’s Integrated System Plan Step Change scenario – and arguably a little ahead in the near term. For storage, at least, we’re broadly on the trajectory that planners have modelled we need.
On the generation side, progress has been steadier. New wind projects, in particular, are taking longer to progress, leaving the current build mix leaning more towards storage than generation.
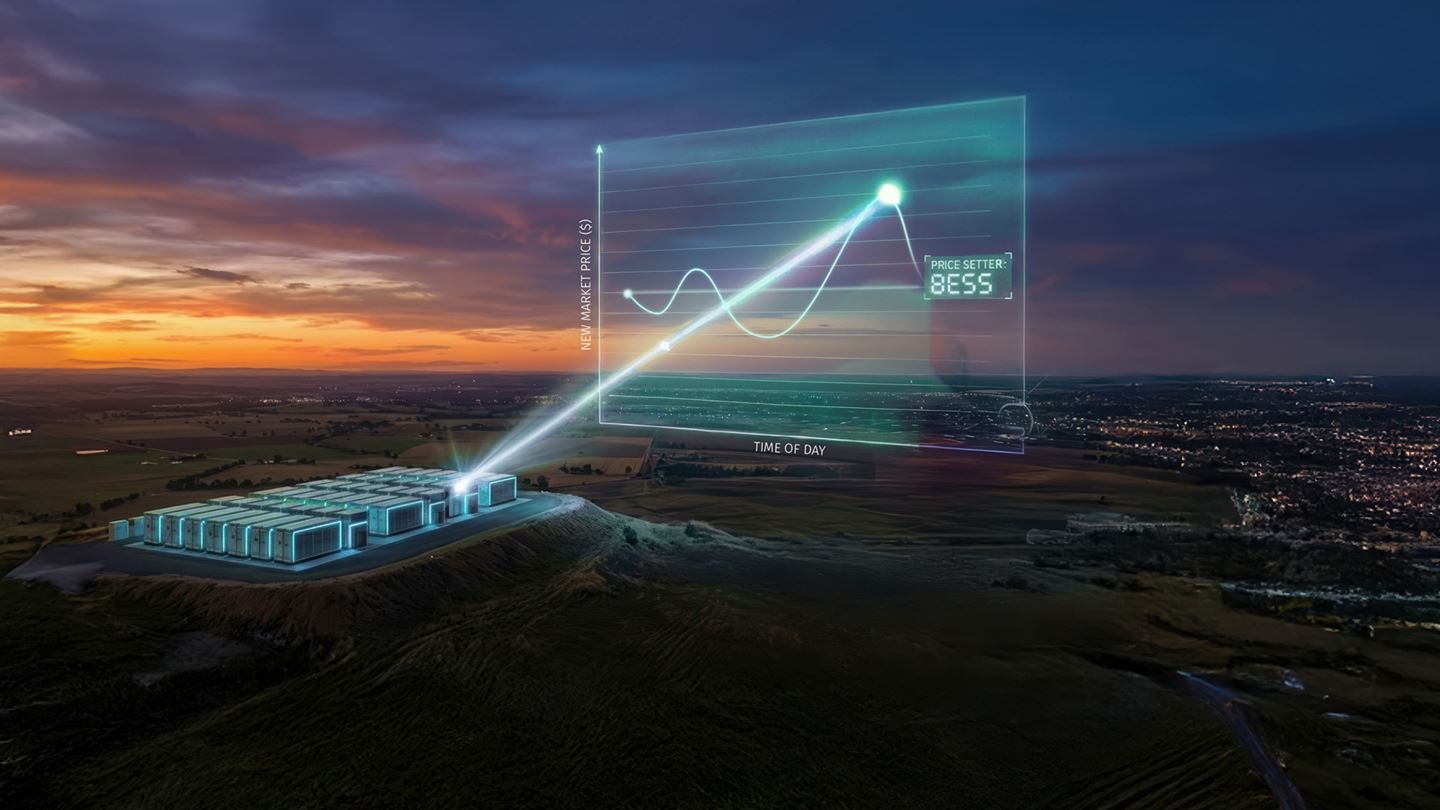
Batteries are no longer just riding the price curve,
they’re the ones drawing it.
What’s changed is not just volume, but role.
Early big batteries were classic price takers: chasing Frequency Control Ancillary Services (FCAS) and picking off occasional arbitrage opportunities. Today, Australia’s battery fleet is starting to shape the energy market itself:
In other words, storage is no longer just reacting to the National Electricity Market (NEM), it’s increasingly designing the intraday price and dispatch profile, smoothing volatility and propping up reliability as coal ages.
Critically, this shift is happening with and without government underwriting. A noticeable cohort of batteries is being financed on private offtake contracting models, while schemes like the Capacity Investment Scheme and state tenders are pulling through a portion of longer-duration projects that sit just below standalone commerciality hurdles.
There is, however, an uncomfortable wrinkle.
The storage fleet – both operating and in the committed pipeline – is heavily skewed toward 2 – 4-hour batteries. For what the market needs today (intraday firming, peak shaving, FCAS), that’s a good fit.
However, zooming out to the system level, it raises a risk that we can easily end up with ‘enough storage MW’ but not enough energy to ride through longer low-renewables events. The maths looks healthy in MW and MWh terms, yet the system is still short of true medium and long-duration, energy-rich capacity.
On paper, pumped hydro and gas firming projects are meant to fill that gap. In practice, while those projects will take their place, they’re slower, lumpier, politically harder, and require a higher marginal energy price. That’s where the current skew really matters.
The good news is that the next wave already looks different.
Across Capacity Investment Scheme rounds and state schemes, there’s a clear pattern: new renewables projects are increasingly being tendered and financed as hybrids, with an integrated battery on site. And those batteries are getting bigger and longer:
New wind and solar won’t sit dormant for long, but the default model for the NEM will be ‘generation + 4-hour BESS’, not standalone PV fields battling negative pricing.
New renewables projects are increasingly being tendered and financed as hybrids, with an integrated battery on site.
Commercially, we’re in a transition zone. A handful of 4-hour projects now stand on their own two feet, financed with offtake agreements based on merchant exposure and portfolio shaping. Others are being pulled through by government tenders and structured contracts, which provide the extra revenue stream they need.
As battery costs continue to fall and market mechanisms evolve to better value firming and flexibility, expect that balance to shift. More 4-hour hybrids will be able to clear on largely commercial terms; schemes like Capacity Investment Scheme will increasingly focus on deeper, more locationally critical or otherwise strategic storage.
The emerging picture is nuanced:
The real test for the next decade is whether we can rebalance: keep this momentum in storage, unlock a new wave of wind and solar, and push part of the fleet beyond today’s 2–4 hour comfort zone into genuine medium and long-duration territory.
If we get that mix right, the current storage boom won’t just be a profitable niche, it will be remembered as the moment storage quietly became the backbone of Australia’s power system.
Design Director & Power Generation Capability Leader – APAC
Australia's energy transition requires more than technical plans. Discover four ways to build the people, culture and capability to deliver infrastructure at scale.
Aurecon’s ecology and biodiversity expert shares how to achieve timely project approvals, what regulators want, and how to navigate regulatory changes.
Aurecon shares insights on how renewable project delivery models are evolving to better manage risk and deliver long-term value through project partnerships.