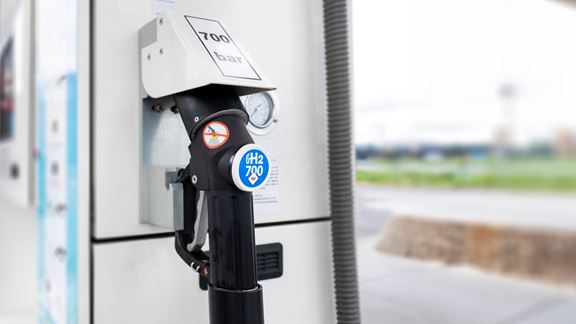
Q&A: What about hydrogen as a future energy, zero-emission technology?
Developing hydrogen as a future energy or fuel presents myriad risks and barriers to be navigated in order to unlock the benefits the technology can provide.


Change your location to view content tailored for you.
At Aurecon, we work with clients who are active across the full spectrum of the energy supply chain.
Our work sees us engage a wide range of stakeholders from technology providers and contractors through to communities, regulators and policy makers. As such, we are in a unique position that touches each of the elements that impact the transition to a lower carbon economy and the potential of hydrogen in the context of a National Hydrogen Strategy for Australia.
Many of our clients anticipate a future energy market in Australia that consists of increasingly distributed sources of supply both for power and gas. Many of our clients also believe that the domestic energy market will increasingly electrify where possible, in particular as the light vehicle fleet is expected to switch from petrol and diesel engine vehicles. With Australia’s relatively small market for electricity on the one hand, and almost unparalleled access to natural resources on the other, the potential for hydrogen to underpin a significant wave of future export revenue and natural gas alternatives for industry is significant.
For many energy market participants, not just in Australia but globally, the re-emergence of interest in the hydrogen economy is less of a priority. The advent of low cost lithium ion battery energy storage devices, both at household and utility scale, is believed by many participants to have put paid to the question of whether hydrogen will emerge as a competitive and compelling alternative energy carrier.
We are asked: what has changed and why will it be different this time around? To answer that question, power and transport industry specifics need to be considered within the global energy and commodity market context.
In Australia, we have access to world class renewable energy resources that far outweigh our ability to utilise them for our own purposes. This is a similar story with other commodities: Australia exports around 80 per cent of our annual coal production; almost 100 per cent of our annual iron ore; 100 per cent of our uranium; and around 60 per cent of our wheat crop[1].
For countries that do not possess the endowment with sunshine, wind and bioenergy, the possibilities of expanding our export and balance of trade to include renewable energy is immensely attractive. This is particularly so for our existing partners in energy coal and iron ore – principally Japan, China, South Korea[2].
While these nations may have regions wherein solar and wind or other forms of renewable energy are bountiful, Australia’s sparse population, available land area, potential supply of water – including via desalination for coastal based export projects – provides us a potentially sustainable competitive advantage and a material marketing differentiator in a world where long term, hydrogen’s share of world energy consumption becomes significant. This context and the critical importance of diversifying our export revenue base away from fossil fuel intensive commodity exposure over time is the first and potentially most important factor in developing a National Hydrogen Strategy. It’s the ‘why’.
Which leads to what we believe is the second most important factor in developing a National Hydrogen Strategy – which is the ‘what’ and refers to the two key requirements for low cost and scalable production of hydrogen, which are electricity and water. For the production of hydrogen, on a scale that meets the guiding strategy development principle of being bold and ambitious, power and water requirements are material[3]. The critical success factor in ensuring access to reliable and low cost power and water supply without downstream impacts on domestic power and water consumers, is fact based, timely and transparent stakeholder engagement.
Aurecon advocates pursuing a suite of government initiatives to ensure a successful holistic approach that see our technological, commercial and industrial interests enabled to take an appropriate level of risk at the right time.
This includes the following priorities and principles:
Establish a focus on technology as the enabler to a green hydrogen economy and leverage the nation’s tertiary education institutions into demonstration projects on both the supply (cost) and demand (revenue) side.
The inefficient duplication of resources and effort between parallel and competing projects has become somewhat of a hallmark in Australia’s recent history of developing and delivering major energy projects. A coordinated and unified approach focussing on optimum long-term market outcomes over short term milestones, and an approach that demonstrates to the many and varied potential markets for hydrogen – power, light vehicle fleet, heavy vehicles, industrial fuel switching – is key.
An effective pathway to developing a hydrogen industry must see a meeting of industrial, agricultural and climate policy to create a seamless and long term plan for each State and Territory.
This must be linked to the various government’s renewable energy and carbon trajectories; public transport services and infrastructure delivery as well as long term export revenue opportunities from coal, minerals and natural gas exports.
Prioritise fringe of grid and remote locations to deliver efficient outcomes at the demonstration scale for power-hydrogen-power opportunities may provide quick wins and maximise early learnings.
For example, these types of facilities could lower network losses, displace local liquid fired generation and make demonstration projects more competitive in the local context.
The narrative regarding our ability as a nation to play a leading global role in the hydrogen sector is compelling. This is particularly so for remote and regional communities where uncertainty regarding the future of energy and mining projects, urbanisation and drought have huge social impacts.
Interest in hydrogen as a means of decarbonisation while maintaining energy security has recently re-emerged for global economies. Japan’s desire to move away from nuclear power generation without sacrificing energy security has spurred its commitment to become the world’s first ‘Hydrogen Society’. South Korea has followed suit with its own ambition to transition to a hydrogen economy. At a smaller scale, the city of Leeds in the UK has a similar aspiration with its H21 Project.
The growing global support led to the formation of the World Hydrogen Council, now supported by some 33 multinational corporations across the hydrogen, oil and gas, transport, power and technology research sectors alongside a further 20 corporations within the value supply chain. The appetite to develop global supply chain networks provides an opportunity for hydrogen development to underpin a long term and valuable export market supply, particularly in Australia, which to date has not existed.
These are two significant recent developments on the demand side and help provide confidence for Australia in answering the question: will demand for hydrogen emerge and to what extent (and when)? On the ‘supply side’, recent advances in technology and the performance of these in the context of various elements in the hydrogen supply chain – from electrolysis, fuels cells, longer term storage and transport – have provided clearer pathways to the necessary reduction in equipment lifecycle (capital and operating) costs. In Australia in particular, the rapid decline in the costs of utility scale solar projects, the emergence of grid scale battery technology to provide a range of benefits to not just renewable energy projects but the network operations, provide an analogue to what could be possible with hydrogen, in support of the question: will the technology challenges be overcome and can the cost structure decrease such that hydrogen will be a viable alternative fuel?
Closer to home, the progress made in demonstration projects both in the transport sector (including the ACT government hydrogen bus trials), power market (including SA’s Renewable Technology Fund support for network connected hydrogen projects) and gas networks (including ARENA’s support for NSW and WA trials) is highly encouraging. As these projects come online and achieve commercial operation, their ability to demonstrate a range of operational and specifically customer focussed benefits will be significant for the industry.
The production and storage of hydrogen is not a new development per se, given that hydrogen has for decades been used at power station facilities as a cooling medium for generators and in industrial / petrochemical facilities using conventional production methods. Community perception around safety of hydrogen production, storage, refuelling facilities, and infrastructure is, however, something that will require careful management as part of a project by project stakeholder engagement and awareness processes in parallel with the project development.
One of the ways to increase the growth of the hydrogen industry is to shift community perception of hydrogen as a highly dangerous fuel source to one where hydrogen risks are recognised and adequately managed. For example, consumers are comfortable using petrol or diesel vehicles despite the flammability risk of these fuels, and risk warnings at petrol stations are one way of ensuring the key risks of refuelling are managed.
Transparency and open acknowledgement of the risks – but also clear mitigation measures – are likely to best create an environment where an emerging industry can build and consolidate a social licence to operate.
Established planning, regulatory and safety in design requirements such as the following are in all cases applicable to managing hydrogen production and storage projects and require highlighting:
It should be noted that if risk perception is the sole driver of the community engagement process, there is a chance that, if not properly understood, investigated and managed, heightened community risk perceptions could lead to over-regulation and standards imposed on hydrogen and related infrastructure that are not relative to the inherent risk. The outcome of such over regulation would be to impose significantly prohibitive costs for an emerging industry.
We expect that the primary technology for the production of hydrogen for export will be the electrolysis of water, that is, using electricity to ‘split’ water molecules into hydrogen and oxygen.
The sourcing of this water presents a potentially significant community and stakeholder engagement challenge, and if not managed carefully, potentially discrete environmental challenges depending on the location of the electrolysis facility.
It is important to recognise that regions identified as having large renewable resources tend to be either lacking in surface water or are in competition for water with agricultural demands. Desalination provides an opportunity for water supply, particularly in coastal regions proximate to ports for export and where, for most capital cities in Australia, large scale desalination facilities already exist. The energy demand for desalination and the operating costs, however, are high and therefore priority areas for demonstration projects should be focussed on sustainable and ‘ethical’ supply of suitable fresh water supplies which require minimal if any treatment prior to electrolysis. Groundwater resources are a possibility in most areas, particularly in Queensland and North West Western Australia, and the risk of overuse, depletion and competition for water need to be carefully addressed by proponents prior to projects proceeding.
This is especially true for current agricultural demands, and those in drought-affected or drought prone areas. The risk of loss of social license for hydrogen production as it relates to water supply – before the industry can reach scale – could be exacerbated to the extent that a preference or greater policy support be provided to hydrogen over say, agricultural practices when it comes to water access.
Similarly, in respect of the electrical energy requirement for hydrogen: any energy project development that occurs rapidly and at significant scale has the potential to negatively affect surrounding communities. Inflation (and subsequent deflation) of local real estate, loss of the sense of community due to worker influx, difficulty in attracting employees for non-industrial labour and local price inflation are examples of the potential negative impacts often experienced in communities where development is not adequately managed or where social impacts are underestimated. Early, often and ongoing community engagement can assist in mitigating the risk of negative community impacts and to ensure development occurs in a way that optimises the benefits for all stakeholders.
Widespread support cannot be assumed and the presumption that community engagement and backing will be immediate and forthcoming is fraught with risk. Lessons abound in ways government, industry and communities have worked well in Australia on various large scale projects over the years, and similarly, where they haven’t worked well. Ensuring that lessons have been learned from what hasn’t worked well in the past and how mistakes can be avoided in the case of advancing a hydrogen economy should be a key part of the National Hydrogen Strategy.
Like the development of any industry in its emergent form, there are roles for Government in either or both supply side or demand side.
On the supply side, the Government might provide support via initiatives aimed at reducing the risk of developing the underpinning industrial infrastructure for hydrogen as an energy carrier. This can be in the form of, by way of example:
Demand side measures are arguably more compelling for project developers and those looking to scale up production, especially in the context of providing support to access competitive and low cost financing.
Aurecon’s experience via our network of contacts with established and emerging players, suggests that while hydrogen production and storage technology is proven at small scale, the ability to deploy at a fully commercial scale - where equipment supply, power purchase (if required) and project certainty can be most competitive – are oftentimes constrained by the lack of demand stimulus.
Therefore, possible roles for the Government in supporting the hydrogen industry on the demand side include facilitating long term off-take agreements for hydrogen gas supply to existing market participants (industrial gas users, gas pipeline operators, natural gas exporters etc) or committing to a longer term off-take for hydrogen gas supply itself for its own facilities / usage on a set of criteria over time that minimise risk to Taxpayers. An analogue for this support is the recent ARENA solar funding round which we believe forms a solid basis for a targeted and near term federal government initiative.
As we’ve described in our responses to other questions posed by the taskforce, on the demand side, a critical success factor is ensuring that our long term trading partners for energy commodities such as thermal coal and liquified natural gas – principally Japan, China, South Korea – are engaged and progressing with their domestic energy market transformation in favour of hydrogen.
On the supply side, significant volumes of low cost power and water are required, as well as competitive construction and operational environments that reduce capital and operating cost exposures.
Careful consideration therefore need to be given to the location of export facilities to take into account these three factors:
The total hydrogen supply chain is extensive, suggesting there are multiple further opportunities for economic growth should hydrogen production commence at scale. A number of industries rely on hydrogen as a feedstock, the largest of which are the production of ammonia and steel. While steel manufacturing has largely moved out of Australia in recent years due to difficulties in competing in price internationally, a new opportunity could be created to supply low emission steel and indeed green ammonia, both for Australia and overseas.
The opportunity also exists to further develop or manufacture energy conversion technologies such as electrolysers and fuel cells, technologies whose manufacturing is currently limited to a select few nations who have had concentrated efforts on hydrogen development. Using a ‘demand stimulus’ locally, whether that be by supporting hydrogen in transport, manufacturing or the power sector, and tying funding support to the relocation of operations for a global supplier of technology to Australia, could be one avenue for driving commercial development and enhancing local R&D outcomes.
The application of hydrogen to remote and energy intensive operations such as mine sites also presents a significant opportunity for the mining sector to decarbonise and in some instances may reduce costs. A number of operations currently rely on fossil fuel generators which can be costly to supply. Alongside this could be the potential to increase exploration and development efforts for those technologies commonly used in hydrogen operations, for example platinum and associated platinum group elements. The concept of focussing efforts on the ‘whole of supply chain’ and ensuring our other natural competitive advantages in mining and minerals are engaged in the hydrogen conversation is part of the ‘whole of Government’ approach that is required, given various States and Territories have different natural competitive advantages.
Finally, there are a number of locally congested regions in not just the east coast electricity market but in the various markets located in Western Australia. Expanding the volume of renewable energy in some of these locations is not an option due to grid constraints, loss factors, and the stable operation of the networks. Using clean hydrogen as a locally generated energy carrier (generated at site by those projects ‘at risk’ of not being able to sell their electricity) and storing it to then generate (either by fuel cell or combustion) dispatchable energy at other times when the grid is not constrained, could lead to overall better outcomes for all projects in those regions or sub-regions and provide the impetus for additional energy project investment.
The key challenges to development of a clean hydrogen industry relate to the nature of the investment landscape for hydrogen. Hydrogen is an energy carrier and as such, is not an ‘energy source’ but a means of transporting / transmitting energy from one location (or form) to another. Like electricity, which must be produced from a source of energy, the competitiveness of hydrogen supply relates to a number of factors inherent to its production.
Most people think of hydrogen sourced from the electrolysis of water, whereby a water molecule is split into hydrogen and oxygen, with the hydrogen stored or transported such that it can be recombined ‘on demand’ either via combustion or via fuel cells to produce heat or electricity respectively. This is not the only source of hydrogen however.
Other sources of hydrogen include bioenergy and of course, fossil fuels ie hydrocarbons in the form of coal, liquid (eg oil) or gas (ie natural gas). In the case of these sources of hydrogen, the relative carbon impact of hydrogen production is dependent on the fuel source (including from bioenergy) while in the case of electricity, how that electricity is produced (ie from either fossil fuel generation or renewable resources such as solar and wind).
Therefore, one of the key challenges to the development of a hydrogen innovation system is market knowledge of how hydrogen is sourced, stored, transported and ultimately used. Differentiating between ‘clean’ or ‘green’ hydrogen and other forms, and justifying why it should be chosen over others is important.
A fundamental view on the importance of hydrogen for the customer is a key gap / barrier to greater focus and attention on it as a fuel source. Parties seeking to develop the industry must make a compelling argument as to how it will benefit customers – be they industrial, commercial or residential gas or electricity customers – as well as other stakeholders and value chain participants such as electricity generators, transmission and distribution companies.
Building on this first challenge / element therefore the main barriers to the use of hydrogen include:
Aurecon would like to reference here two examples of how the combination of clear objective and supportive regulatory environment was able to drive successful processes and outcomes at a national level.
The first is the Australian Renewable Energy Agency (ARENA) run large-scale solar investment programme.
In order to accelerate the deployment of large scale solar, ARENA’s funding round called for projects to come forward and request capital grants tied to those projects meeting a discrete target for the cost of energy.
The target price was transparent, common financial models were used for evaluation purposes, and the co-investment pulled forward enabled almost 500MW of utility solar projects to be deployed. In the Australian context, this funding round achieved two key outcomes:
This has enabled the industry to dramatically lower the price of energy from a utility solar farm from almost $200/MWh in 2013 to $135/MWh (the target under ARENA) in 2015 and to levels approaching $50/MWh and below in 2019.
A second relevant analogue demonstrating where lowering costs and shortening timeframes can be achieved with a coordinated approach is the Queensland Gas Scheme, introduced in 2005. With the express aim of increasing the per centage of gas fired generation in the state, accredited gas fired generators were able to create Gas Electricity Certificates (GECs) for each MWh of eligible gas fired power they produced.
This scheme gave natural gas exploration companies additional confidence in undertaking the costly and risky early exploration phase in the gas supply chain, in order to meet what was then an equivalent target of around an additional 1,000 MW of gas fired generation.
By creating a strong demand signal, the supply side was able to plan and methodically take appropriate risks at the appropriate time. This led to a number of exploration companies making investments to secure, explore and ultimately deliver coal seam methane production, which in turn led to the realisation of a significant resource base for coal seam methane within the state.
This arguably created the supply side conditions such that international market demand for liquified natural gas (LNG) from coal seam methane was able to be realised with long term supply agreements executed. This in turn drove the delivery of the valuable pipeline and export terminal infrastructure within the state.
While a number of lessons have been learned regarding competition for resources and staff, and the impacts of a lack of collaboration and coordination across the various parties involved in delivering these assets, it could be argued that the ‘realisation’ of Queensland’s vast natural gas resource base was sparked by the introduction of GECs as a means of diversifying its electricity mix.
The possibilities that might arise in the pursuit of a national approach to hydrogen – via industrial, transport, power market support mechanisms – could deliver similar upside potential if well planned and executed.
Given Australia’s proven ability to demonstrate the value of our commodity exports, and channel them to global markets, our strength in marketing and delivering ‘product’ to customers is an important consideration in understanding where we start in the competitive landscape.
Our local industries, too, have proven ability to – when the rules and regulations are known – deliver on key targets that are set. One particularly relevant case is the federal Renewable Energy Target (RET), being a certificate trading scheme that sets obligations on retailers and certain customers of electricity to deliver against known targets for annual and overall renewable energy volumes. Australia is on track to deliver against what was, at the time and until as recently as 2014/2015, an extreme logistical challenge in terms of managing the installation of GW worth of wind and solar farms. Yet with just over a year to go until the 2020 deadline, the industry is on track to achieve and ultimately exceed its requirement. The ability of Australian commercial interests to deliver on development targets is a key strength and in the event of credible targets being set for a ‘hydrogen industry’ we have confidence that these interests can mobilise to achieve, if structured well with clear obligations.
The key challenge to development of a clean hydrogen industry, further to those specific challenges already outlined in our submission, will be aligning on a credible and tangible end goal, with an achievable pathway that does not adversely position existing or competing interests such as hydrogen production from conventional means (often referred to as ‘blue hydrogen’ or hydrogen from steam reforming of natural gas). However, we do commend the plan outlined by the Taskforce for providing clear visibility of the milestones and timing of this process.
Australia has a deep skills base in conventional mining, minerals processing, bulk handling and export industries, with this skills base mixed depending on the State, Territory or sub-region. Australian companies have the necessary commercial and trading expertise to support international engagement in order to develop the export demand channels required. Given the material build experienced in the Australian renewable energy industry this last decade, as well as the ability of the various networks to integrate and operate these plant, Australia’s expertise in the power industry is particularly current and relevant.
The associated training to grow a sustainable hydrogen industry in Australia will be based around the specific regions in the nation where hydrogen is produced, that production method (be it electrolysis or other) and ultimately the end use for hydrogen itself. These are envisaged to include:
Working with industry and higher education institutions to ensure that relevant training includes a hydrogen component to engineering degrees, as well as on the job training for specific operation and maintenance requirements / skills diversification for the many employees presently employed in the power and utilities sector will also be critical.
In our response to prior questions, we have highlighted that one of the key challenges to deployment of hydrogen projects is the cost competitiveness of hydrogen as an energy carrier.
In the case of hydrogen produced via electrolysis of water, these factors can be described as: the price of electricity input, capital cost of the equipment and the cycle roundtrip efficiency relative to other forms of production, storage and recombination.
The gaps in our knowledge primarily relate to the integration of the various ‘elements’ in the hydrogen supply chain, that is, how projects are brought together through production, storage, transport and delivery to the customer (as fuel or via power).
Aurecon is not typically involved in the research and development space as it relates to novel technologies for production, storage or transport of hydrogen. With Australia’s history in mining and minerals processing research and development, we believe a significant opportunity exists to understand how the existing and emerging commodity supply chain for hydrogen production and storage (specifically, the requirement for metals and other materials for componentry manufacture) presents a key gap that plays to our strengths.
[1] Department of Industry, Innovation and Science; Resources & Energy Quarterly Dec 2018; Dept of Agriculture and Water, Fact Sheet Jan 2018
[2] Minerals Council of Australia, Commodity Insights, June 2018
[3] Aurecon presentation to Australian Domestic Gas Conference Hydrogen Day, 7 March, showing indicative volume of energy for a notional 40MTpa export industry is 10 x the current National Electricity Market annual demand (approx. 2000TWh) and around ~250GL/year of water (equivalent to total annual QLD great artesian basin water extraction volume). 40MTpa is approx. 10% of forecast total additional global market for hydrogen according to World Hydrogen Council, 2018. Is it ‘bold and ambitious’ enough?
Developing hydrogen as a future energy or fuel presents myriad risks and barriers to be navigated in order to unlock the benefits the technology can provide.
The transition to hydrogen is expected to play a significant role in the deep decarbonisation of industries. What are the key opportunities now for organisations?
Hydrogen plays an integral part in a decarbonised future. How do organisations innovate their business models to meet shifting market priorities?